Written Commentary
CORN
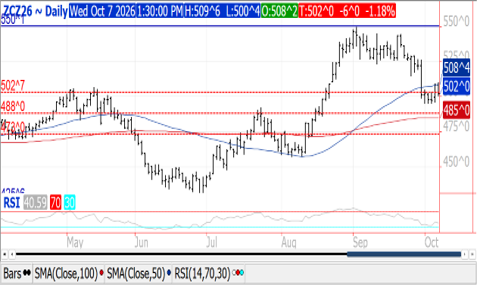
Prices were $.04-$.06 lower while spreads also weaken. Dec-26 rejected trade above yesterday’s high before pulling back to the midpoint of yesterday’s range. Support below the market is at $4.88. The Reuter’s poll shows the Ave. production estimate at 15.721 bil. bu. with stocks at 1.670 bil., very much in line with our expectations of production at 15.710 bil. and stocks at 1.695 bil. Brazil’s corn shipments in Sept-26 reached 5.2 mmt, down 31% YOY. US ethanol production jumped to 310 mil. gallons last week, up from 296 mil. the previous week while down 1.7% YOY. There was 103 mil. bu. of corn used in the production process, or 14.77 mil. bu. per day. In the MY to date there has been 473 mil. bu. used, or 14.8 mbd, an annualized pace of 5.391 bil. bu. well below the USDA forecast of 5.60 bil. bu. Stocks slipped to 23.7 mil. barrels, still above 22.7 mb from YA. Production margins surged in the past week on higher ethanol prices combined with cheaper corn. Since 1990 the USDA lowered corn yields in August and September eleven times, with this year being the 11th. In the previous 10 years the USDA raised yields in October 5 times, lowering them 4 while holding them unchanged once. Tomorrow’s export sales are expected to range from 25-65 mil. bu.
SOYBEANS
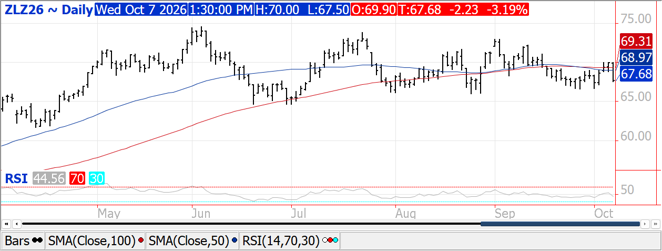
Prices were mixed with beans down $.04-$.06, meal jumped $8-$11 while oil plunged over $.02 lbs. Bean spreads weakened, meal spreads firmed while oil spreads were mixed. Nov-26 beans are back below $13 wanting evidence of addition sales to China. Dec-26 meal surged to a fresh 2-week high. Dec-26 oil sliced through its 50 and 100-day MA’s while again failing to trade above $.70 lbs. Next support is the Sept-26 low at 66.61. Crush margins improved $.04 ½ to $2.51 ½ bu. with meal PV jumping to 51.9%. Dry for much of the Midwest this week which should enable harvest progress to get back on track. Tropical storm Isaias is expected to reach strength 2 hurricane status tomorrow before making landfall along the central Gulf coast this weekend, likely causing brief shipping delays. Heavy rain with potentially damaging winds are expected for the SE and Delta region while possibly bringing heavy rain to Southern areas of the ECB by Sunday. The Reuter’s poll shows the Ave. production estimate at 4.534 bil. bu. with stocks at 305 mil. just above our expectations of production at 4.510 bil. and stocks at 290 mil. While Chinese purchases have slowed since late Sept-26, perhaps the return from Golden Holiday tomorrow will change that. Purchases for the 2026/27 MY likely between 14-15 mmt. US Gulf FOB offers remain $.20 below Brazilian offers through the end of the year. By Jan-27 Brazilian offers are $.80-$.90 below US. Brazil’s soybean shipments in Sept-26 at 7.36 mmt are steady YOY. Soybean O.I. was up nearly 11k contracts while meal was down 2.5k and oil up 2.1k. The USDA lowered yields in August only to raise them in September eight times since 1990. In the previous 7 years yields rose in October 4 times, were lowered 2 times, while held unchanged once. Tomorrow’s export sales are expected to range from 16-44 mil. bu. of soybeans, 150-600k tons of meal and 0-6k tons of oil.
WHEAT
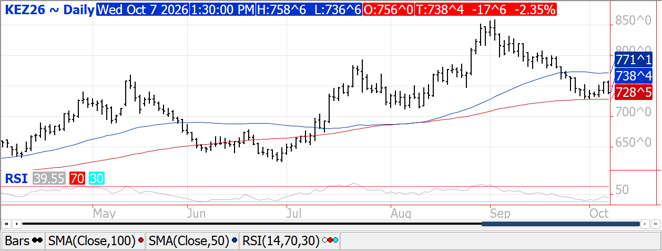
Prices were $.10-$.18 lower today, giving up all of yesterday’s gains. CGO Dec-26 was down $.17 ¾ at $6.86 ½ rejecting trade above its 50-day MA. Dec-26 KC was $.17 ¾ lower at $7.38 ½, while Dec-26 MIAX was $.09 ½ lower at $7.10 ¼. IKAR reports Russian shipments thru the Baltic region reached 1.4 mmt in Sept-26 with the potential to rise to 1.8 mmt in Oct-26. Russia struck 2 more vessels in the Black Sea off the coast of Bulgaria. The crew from 1 of those vessels is still missing. This comes a day after Russia struck a vessel off the Romanian coast. Both countries are NATO members. The Rueter’s poll shows traders expect 2026/27 US wheat stocks to rise only 4 mil. bu. to 721 mil. vs. our estimate of 735 mil. Open interest in CGO was up over 7k contracts while down 1.7k in KC. Tomorrow’s updated US drought monitor is likely to show continued easing of drought conditions across WW growing areas. Export sales are expected to range from 8-18 mil. bu.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
