Written Commentary
CORN
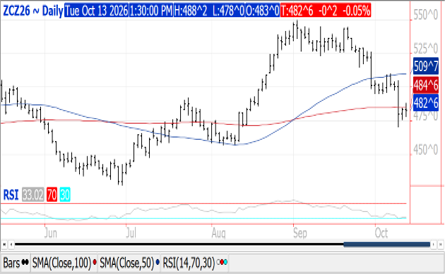
Prices were $.01-$.02 lower while holding within yesterday’s range. Spreads were steady to firm. Dec-26 futures rejected trade above its 100-day MA yesterday while holding support above Friday’s low. Longer term support is at the August low at $4.57 ¼. Corn ratings improved 2% to 56% G/E. Composite ratings improved in 6 states, declined in 4 while holding steady in 8. Harvest advanced only 10% to 33%, the slowest pace in 7 years while below the 5-year Ave. of 39%. Biggest delays are in IA at 14% vs. 34% Ave., SD at 15% vs. 31% Ave. and MI at only 4% vs. 22% Ave. Updated ratings and ear population data suggest an average US yield of 179.3 bpa with production at 15.865 bil. bu. up 107 mil. from last week while below the USDA forecast at 16.034 bil. bu. Ukrainian farm union UAC expects they will only be able to export 18-19 mmt of corn in the 26/27 MY, below the USDA forecast of 22 mmt. France’s Ag. Ministry lowered their corn production forecast another .8 mmt to 7.3 mmt, roughly have of the 2025 harvest. I look for US exports to pick up as US Gulf FOB offers are competitively prices with Argentina while falling $10 per ton below Brazilian offers.
SOYBEANS
Prices were mixed with beans down $.06-$.09, meal was steady to $1 higher while oil was down nearly $.01 lb. Nov-26 beans held support above its 50-day MA at $12.71 ¾ while Dec-26 oil held support above last month’s low at 66.61. Bean oil has been under pressure since the EPA yesterday announced they would reallocate 100% of the 1.76 bil. RIN’s from 2025 SRE’s. What’s not know is if they will be divided equally between 2026 and 2027, or all in 2027. The USDA announced a flash sale of 470k tons (17 mil. bu.) of soybeans to China, their first large purchase since the Xi/Trump meeting in Washington 3 weeks ago. I suspect their purchases are now between 15.5 and 16 mmt. China imported 11.88 mmt of soybeans in Sept-26 from all sources, down 7.7% YOY and down 2.1% from Aug-26. YTD purchases at 86.1 mmt are down less than 1% from YA. China’s Sinograin will auction off another 504k mt of state-owned soybean reserves on Oct. 20th. Monday’s auction sold only 40% of the 518k tons offered. COFCO claims their crush industry is experiencing severe overcapacity as their meal consumption has likely plateaued with wider acceptance of low-protein feed technologies. After being sharply lower at midday, crush margins recovered to finish down $.01 to $2.62 ½ bu. with meal PV improving to 52.1%. Crop ratings held steady at 57% G/E. Ratings improved in 11 states, declined in 5 while holding steady in 2. Harvest advanced 21% to 46%, still behind the 5-year Ave. of 50%. Most noted delays are in IA at 31% vs. 59% Ave. and NE at 26% vs. 55% Ave. Updated ratings and pod count data suggest an average US yield of 52.6 bpa with production at 4.516 bil. bu. up 23 mil. bu. from last week while below the updated USDA forecast of 4.562 bil.
WHEAT
A late recovery in CGO and KC futures enabled wheat to scratch out a mixed close. CGO Dec-26 was up $.04 at $6.73 ¼ after holding support at this month’s low of $6.61 ½. Dec-26 KC was up $.02 ¾ at $7.15 after holding support above $7.00. Dec-26 MIAX was $.04 lower at $6.90, slipping to a 2 ½ month low. Algeria reportedly bought between 600-720k mt of milling wheat near $326/mt CF. The grain was likely sourced from Russia via Baltic ports, along with Romania, Bulgaria and Argentina with shipment expected in December. EU soft wheat exports as of Oct. 11th at 8 mmt are off 27% YOY. Ukraine’s largest farm union expects they will export no more than 11 mmt of wheat in the 26/27 MY, down from 14 mmt YA and below the USDA estimate of 12.5 mmt. Since July they have shipped only 3.13 mmt, down 44% YOY. US winter wheat plantings advanced 15% to 51%, still below the 5-year Ave. of 58%. With prices across the 3 classes $1.30-$2.00 off their recent highs, I see limited downside risk unless the Black Sea reopens. Upside potential also limited as global buyers still haven’t shifted to US while drought conditions in the Plains will likely continue to ease.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
