Written Commentary
CORN
Prices closed $.02-$.04 higher, drifing back a bit into the close while spreads eased. With spot futures jumping out to a 3-year high this week, next resistance is the 38% retracement on the weekly chart at $5.38. After taking a break from heavy buying yesterday, speculative traders were back in a buying mood today. We had the speculative long position at 395k after yesterday’s trade vs. the record long position of 429k from back in Oct-2010. The BAGE held their Argentine production forecast unchanged at 64 mmt, vs. USDA 63 mmt, while reporting harvest progress advanced to 88%. Safras & Mercado raised their 2026/27 Brazilian production forecast slightly to 145.6 mmt, well above the USDA forecast of 139 mmt. The European Commission lowered their EU corn production forecast to 50.1 mmt, the lowest in nearly 20 years while down 17% YOY. They also raised their import forecast 1 mmt, to 25 mmt, this being made more difficult as historically 50-60% of their corn imports have come from Ukraine. Corn ratings in France slipped to only 28% G/E, vs. 62% YA. Expectations for lower US production and higher usage leaving US and global stocks much tighter than current USDA forecasts continue to fuel the higher trade. So far, the seasonal high in Dec-26 corn at $5.41 ¼ is up 21.6% from the Q1 low, still below the historical average of up 25%.
SOYBEANS
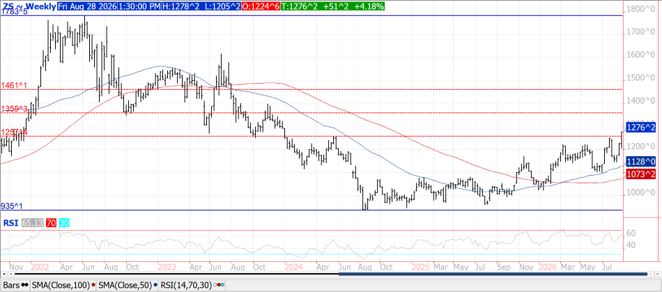
Prices were higher across the complex with beans up $.17-$.20, meal was $5-$8 higher while oil was just over $.02 ½ lbs. Spot Sept-26 beans traded through its 38% retracement level on the weekly chart with the 50% retracement at $13.59. Oct-26 meal traded to its highest level in 2 years driven by flash sales to Europe. Oct-26 oil traded to new highs for the week while holding above its 50 and 100-day MA’s. Crush margins have surged $.26 ½ to $2.46 ½ bu. with bean oil PV just over 51%. The Trump Admin. is reportedly considering raising biofuel blending quotas in 2027 by 500 mil. gallons to offset lower demand from higher SRE’s that are expected to be announced on Monday. This week the Trump Admin. excluded China from Iranian sanctions to allow them additional time to shift energy demand to other suppliers. US Gulf FOB offers continue to hold $.30-$.35 below Brazilian offers. The USDA announced flash sales of 182k mt (6.7 mil. bu.) to China, 226k mt (8.3 mil. bu.) to unknown along with 100k tons of meal sold to each Germany and the Netherlands. Uncertain US production combined with Chinese buying provide little wiggle room for US yields to slip from the current USDA forecast of 52.7 bpa. So far, the seasonal high in Nov-26 beans at $12.90 is up 22.2% from the Q1 low, still below the historical average which is also 25%.
WHEAT
Prices range from $.11-$.24 higher in volatile, 2-sided trade. CGO Dec-26 was up $.23 ¼ at $7.84, KC Dec-26 was $.22 ¼ higher at $8.44 ¼, while Dec-26 MIAX was $.11 ½ higher at $7.69 ¼. Next resistance for spot CGO is the July-23 high at $7.77 ¼. Spot KC futures traded through its 38% Fibonacci on the weekly chart with the 50% retracement coming in at $9.29. This afternoon’s CFTC report may show MM’s still net short CGO wheat as it captures positions through Tuesday’s trade, almost certain they are long at today’s close. Ukraine’s Ag. Minister expects winter wheat acres will be down this fall without providing specifics, as logistical issues continue to restrict grain shipments while drought impacts Southern growing areas. Planted area in Russia is also likely to be lower. Logistical issues are starting to lead to production/supply issues. France loaded its first wheat shipment destined for Sudan in 18 years. US spring wheat acres in drought surged 17% last week to 80%.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
