Written Commentary
CORN
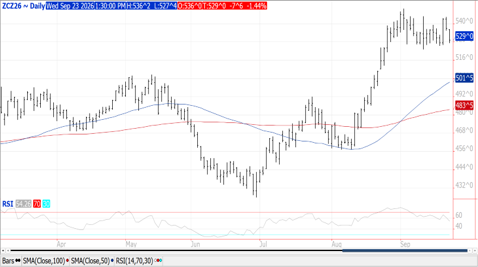
Prices were $.04-$.07 lower while spreads weakened. Despite the lower trade, Dec-26 futures continue to hold within the range from Fri. Sept. 11th, USDA report day. First support is at $5.23 ¼. The USDA announced a flash sale of 100k tons (4 mil. bu.) of corn to Mexico. US Gulf FOB offers have spiked vs. SA prices, perhaps an attempt to shift non-Chinese buyers to Brazil or Argentina in the event China starts buying up US grain. If China were to purchase US corn it would be purely for political reasons as Dalian prices have fallen to only a $70 per ton premium to US Gulf prices, matching the low from 2025 and the lowest since the spring of 2022. Coceral is forecasting combined EU and UK corn production at 48.6 mmt, down 14% YOY. The BAGE forecasts Argentina’s 2026/27 production at 66 mmt, above this past year’s record production of 64 mmt. Ethanol production fell to 302 mil. gallons last week, down from 323 mil. the previous week, while up less than 1% YOY. Production was the lowest in 5 months and below expectations. There was 101 mil. bu. of corn used in the production process, or 14.4 mil. bu. per day. In the MY to date there has been 270 mil. bu. used, or 15.0 mbd, an annualized pace of 5.484 bil. bu. below the USDA forecast of 5.60 bil. bu. Stocks dipped to 24.7 mil. barrels, still above 23.47 mb from YA. Tomorrow’s export sales are expected to range from 32-55 mil. bu.
SOYBEANS
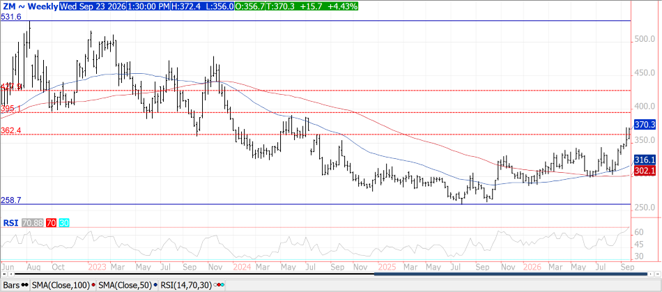
Except for spot soybean meal, prices were lower across the complex. Beans were down $.05-$.08, meal ranged from $1 lower to $1 higher while oil rebounded to close down only 10 points. Beans spreads were weaker, meal spreads firmed while oil spreads were mixed. Nov-26 beans pulled back to roughly the midpoint of this month’s range. Oct-26 meal was unable to penetrate yesterday’s high before pulling back while Oct-26 oil slipped to a 1-month low before recovering. Meal basis levels have spiked, particularly in the WCB, as soybean supplies have dwindled due to heavy rain delaying harvest in the region. Some crushers pulled their meal offers due to lack of supply. Crush margins rebounded $.06 to $2.43 bu. Dry conditions are expected to hold across the central Midwest into early next week with moderate to heavy rains expected to build across the central plains and WCB. Week 2 of the outlook has above normal precipitation across the nation’s midsection. Sinograin announced plans for another auction of 514k tons is soybean reserves from Govt. stocks next Monday. Brazil is expected to ship 8 mmt of soybeans in Sept-26, down from earlier forecasts of 8.3 mmt, however would still be a record high for the month. AgRural reported Brazil’s 2026/27 crop is just over 1% planted. The BAGE is forecasting Argentina production in 2026/27 at 53.6 mmt, up from 50.1 in 2025/26.
WHEAT
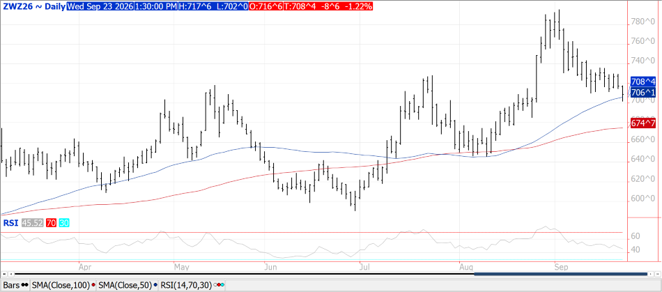
Prices ranged from $.07 to $.10 lower, recovering to close off session lows. All 3 classes violating support at their 50-day MA intraday, while MIAX close below the technical level. CGO Dec-26 was down $.08 ¾ at $7.08 ½, KC Dec-26 was $.09 ½ lower at $7.71 ¾ while Dec-26 MIAX was $.07 ½ lower at $7.28 ¾. Russian and Ukrainian forces continue military strikes on port infrastructure and cargo vessels despite hopes for a peaceful solution after Pres. Trump met with Ukraine Pres. Zelenskyy in NY yesterday. Overnight Russia’s Defense Ministry claim to have struck 2 logistic centers in Odesa while also striking a dry cargo vessel. Ukraine’s Ag. Minister reports their wheat harvest is complete with 25.3 mmt gathered, up 11% YOY. They also report 26/27 plantings have reached 14.6%. Russia’s WW plantings at 6.1 mil. HA is down 14% from YA pace at 7.1 mil. HAC and the slowest since 2013. Coceral is forecasting combined EU and UK wheat production at 137.5 mmt, down 7.5% YOY. The BAGE is forecasting Argentina production in 2026/27 at 23.4 mmt, down from 27.8 mmt in 25/26. The lowest offer for Tunisia’s 125k mt wheat tender was $311.72/mt CF while no sales yet reported. US export sales are expected to reach 12-22 mil. bu.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
