Written Commentary
CORN
Prices closed $.02-$.03 lower in choppy 2-sided trade, unable to hold early strength. Spreads were little changed. Dec-26 shrugged off sharply lower trade yesterday, rebounding after posting 6 consecutive lower closes. We had the money manager long position at 186k contracts at yesterday’s close, probably down a couple more thousand today. Friday’s COF report is expected to show cattle inventories at 11.441 mil. head as of Oct. 1st, slightly above 11.418 mil. YA. Placements are expected to be down 8.3% while marketing off 7.3%. Brazil corn shipments to Europe surged to 1.65 mmt in Oct-26, up from only 200k tons in Oct-25. SovEcon slashed Ukraine’s corn exports another 18% to 17.2 mmt, vs. the USDA est. at 22 mmt. The Rosario Grain Exchange held their 2026/27 Argentine corn production forecast steady at 67.5 mmt, well above the USDA est. at only 55 mmt. Quite the discrepancies between USDA production forecasts in SA compared with RGE and Conab. US exports at 60 mil. bu. were at the high end of expectations. YTD sales are down 34% vs. the USDA forecast of down 4%. Commitments represent 27% of the USDA forecast vs. the historical average of 36%. Noted buyers were Mexico – 19 mil. bu., Japan – 11 mil. while 12 mil. bu. was sold to unknown. For prices to form a meaningful bounce, we’ll need to see a stronger pickup in demand and/or a more threatening forecast in SA.
SOYBEANS
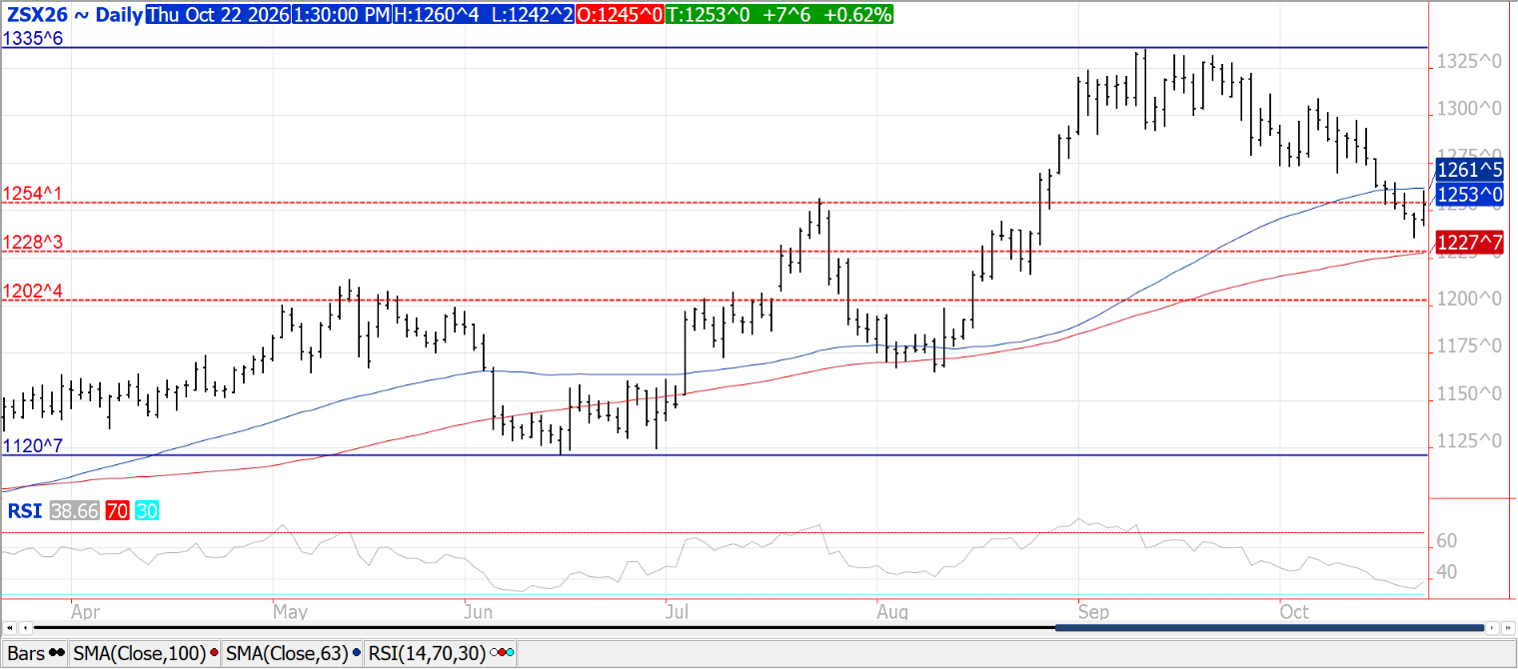
Prices were mostly higher with beans up $.03-$.08 ending a run of 8 consecutive lower closes, meal was steady to $1 lower while oil was up 80 points. The early surge in Nov-26 soybeans stalled just below its 50-day MA at $12.61 ½. Support below the market is at $12.28. Yesterday Dec-26 meal rejected trade below its 50-day MA. Crush margins were down $.02 at $2.45 bu. with bean oil PV up to 49%. Soybean O.I. plunged just over 17k contracts yesterday, meal was down 5.7k while oil was up just over 4k contracts. China’s Sinograin will auction off another 512k mt of soybeans from Govt. reserves next Tues. the 27th. US exports at 104 mil. were at the high end of expectations and the highest weekly total in nearly 3 years. YTD commitments are up 81% from YA vs. the USDA forecast of up 12%. Sales to China at 2.18 mmt take commitments to 13.45 mmt vs. zero YA. There are another 5.66 mmt parked in unknown. With another flash sale of 202k mt to China this AM, total commitments are roughly 18 mmt. Meal sales at 242k tons were below expectations. YTD commitments are up steady with YA vs. the USDA forecast of up 11%. YTD bean oil sales at 55 mil. lbs. are down 81% from YA vs. the USDA forecast of down 59%. I believe the USDA export forecast at 1.695 bil. bu. (46.1 mmt) will prove to be too low. With China taking 25 mmt, the current USDA est. leaves only 21.1 mmt for all other non-Chinese buyers, down 27% from YA. YTD commitments to non-Chinese buyers are down only 10%. US Gulf FOB offers are holding $.20-$.40 below Brazilian offers into year end. The RGE held their 2026/27 Argentine soybean production forecast steady at 47.8 mmt vs. the USDA at 50 mmt.
WHEAT
Prices ranged from $.04-$.10 lower with KC and MIAX both slipping to fresh 3-month lows. CGO Dec-26 was down $.03 ½ at $6.24 ¾, Dec-26 KC was off $.07 ¼ at $6.65 ¾, while Dec-26 MIAX is $.09 ¾ lower at $6.42. Spot MIAX futures are now $1.50 bu. off their Sept-26 highs. Next support is the June-26 low at $6.25 while the contract low is $6.21. Trilateral talks between US, Russia and Ukraine are slated for Nov. 10th, meanwhile the fighting continues. SovEcon cut Ukraine’s wheat export forecast another 7.7% to 14.4 mmt vs. the USDA est. already down to 12.5 mmt. Ukraine’s exports July through Sept at 3.8 mmt is the lowest in 15 years. IKAR see’s Russian exports reaching 3 mmt in both Oct. and Nov. after reaching 2.5 mmt in Sept. The RGE raised their 2026/27 Argentine production forecast 13% to 23.8 mmt vs. the USDA est. at 21.5 mmt. US winter wheat acres in drought slipped 4% to 49%.
Futures and options trading involve significant risk of loss and may not be suitable for everyone. Therefore, carefully consider whether such trading is suitable for you in light of your financial condition. The information and comments contained herein is provided by ADMIS and in no way should be construed to be information provided by ADM. The author of this report did not have a financial interest in any of the contracts discussed in this report at the time the report was prepared. The information provided is designed to assist in your analysis and evaluation of the futures and options markets. However, any decisions you may make to buy, sell or hold a futures or options position on such research are entirely your own and not in any way deemed to be endorsed by or attributed to ADMIS. Copyright ADM Investor Services, Inc.
